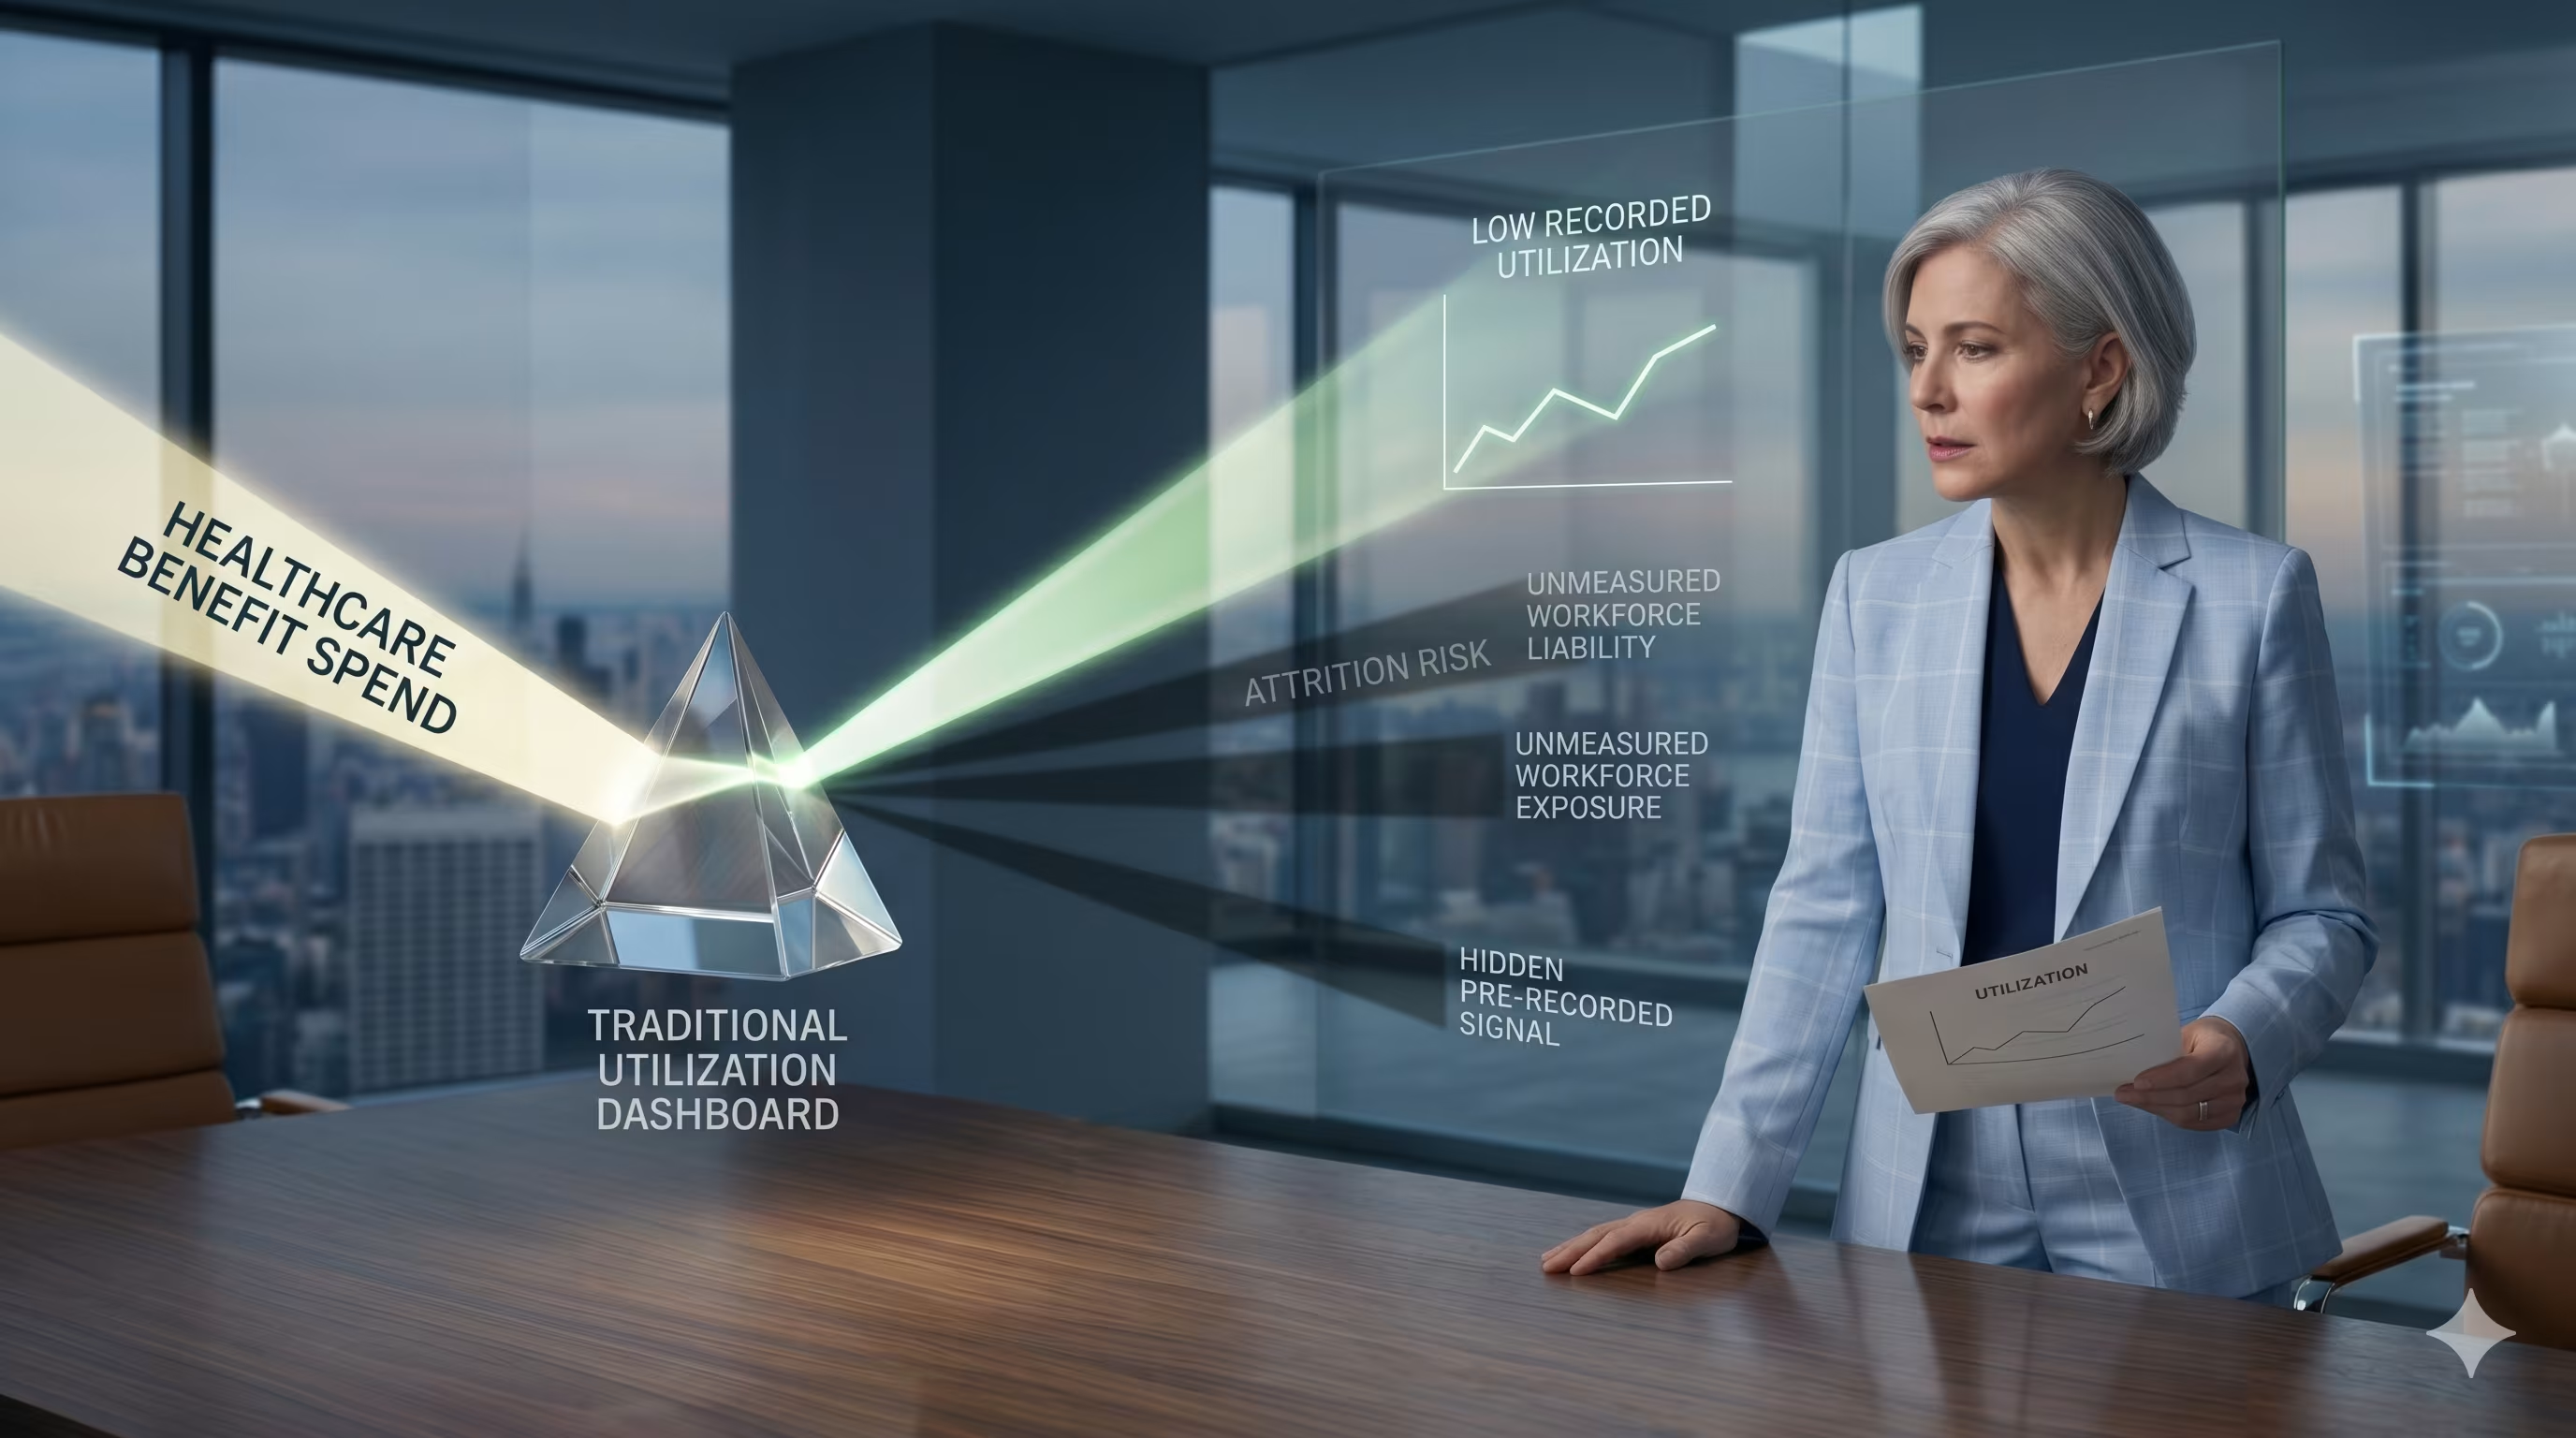
AI ROI cannot be proved when the enterprise cannot reconstruct total cost of ownership. Agent execution, cloud consumption, integration, correction, and retained human work escape the original business case. That is where AI ROI debt begins.
Companies are beginning to admit that enterprise AI returns remain elusive. The next financial problem is more serious: what happens when an AI investment fails to produce measurable value, and the proposed solution is another round of spending?
The answer begins with a denominator problem. An organization cannot determine AI return on investment until it can determine the investment’s total cost of ownership. Yet AI cost does not arrive on one invoice, under one owner, or even inside one budget.
The first expenditure buys the model, platform, pilot, or enterprise license. The second pays for the data preparation, cloud infrastructure, integrations, governance, workflow redesign, employee training, and human review required to make the first expenditure work.
That second cycle is AI ROI debt.
AI ROI debt begins when the organization must keep spending to preserve the possibility that the original AI investment may eventually prove worthwhile.
AI TCO Is the Missing Denominator
Traditional software has a reasonably visible cost structure: license, implementation, support, and a known population of users. Enterprise AI is a changing system assembled from models, data, infrastructure, tools, workflows, controls, and people.
Procurement sees licenses. Engineering sees API calls and cloud resources. Data teams see pipelines and storage. Security sees testing and controls. Operations sees exceptions. Business units see employee time. Finance sees fragments of the cost, often after they have been distributed across several budgets.
The result is a total-cost calculation that captures what is billed directly and excludes what the organization absorbs indirectly.
AI TCO extends beyond tokens and tool licenses. It can include cloud and inference consumption, data preparation, integrations, cybersecurity, governance, monitoring, correction, exception handling, retained human review, vendor management, and eventual migration or termination.
No single omitted item appears fatal. Together, they can invalidate the original business case.
AI Agents Make the Cost Harder to See
Agents make this denominator more unstable because one employee request does not necessarily produce one billable action.
An agent may retrieve context, call a model repeatedly, invoke external tools, delegate to another agent, retry failed steps, validate its own work, and then send the result to a person for approval. The user sees one request. The enterprise pays for an execution path.
That path can generate model, cloud, data, tool, monitoring, and human-review costs in several systems at once. It can also change without a new procurement event when a model, prompt, tool, or workflow is updated.
This is why cost per token, seat, or agent run is not enough. The financially relevant unit is the cost of a completed and accepted business outcome. A cheap run that fails is not cheap. A completed run that requires senior correction is not autonomous.
AWS’s own agent cost examples separate model inference from runtime, memory, infrastructure, vector storage, guardrails, and external tools. The examples reveal the core problem without resolving it: the model bill is only one part of the system cost.
AI Benefits Are Not the Same as AI Returns
The reporting on enterprise AI is not uniformly negative, and that is part of the trap.
Companies are documenting real local benefits: reduced call volumes, faster software development, lower service costs, and improved inventory performance. These improvements may be genuine. They are still not the same thing as enterprise return.
Global Finance reports that only a minority of organizations can demonstrate that AI benefits exceed total investment. The underlying research is stark. An MIT study of more than 300 publicly disclosed generative-AI initiatives found that 95% generated no return against an estimated $30 billion to $40 billion in enterprise investment. A Deloitte survey found that 85% of organizations had increased AI investment, while only 10% were realizing significant returns from agentic AI.
Hold those numbers side by side: spending is expanding much faster than demonstrated return.
A use case can save time locally while the enterprise carries new infrastructure, review, correction, and governance costs elsewhere. Finance is left holding encouraging anecdotes and a denominator it cannot reconstruct.
A benefit is an observation. A return is a calculation. Without total cost of ownership, the calculation is incomplete.
How the Missing Denominator Becomes AI ROI Debt
When an AI investment underperforms, the diagnosis rarely questions the investment. It questions the company.
The proposed remedies are familiar:
- improve the data;
- add integrations;
- strengthen governance;
- redesign workflows;
- retrain employees;
- increase adoption;
- move from experiments to scale.
Each may be operationally reasonable. Each is also a request for additional capital on an investment that has not yet paid for itself.
The explanation performs a specific financial function: it transfers responsibility from the investment thesis to the surrounding enterprise. Once the enterprise is the problem, the rescue budget has no natural ceiling. There is always another dataset to clean, system to integrate, workflow to redesign, or employee cohort to train.
In ordinary capital allocation, an investment that fails to produce its projected return triggers reconsideration: retain, restructure, impair, terminate, or replace. In AI portfolios, the same failure is routinely treated as justification for the next tranche.
The original business case remains formally alive while the cost structure underneath it expands beyond recognition. That is AI ROI debt.
Headcount Reduction Does Not Prove AI Savings
The workforce version of this problem is the hardest to reverse.
Many automation business cases compare employee wages against an AI license. The real comparison is total human operating cost against total AI operating cost plus the human infrastructure still required to make the AI usable.
That second term includes correction, escalation, model monitoring, customer remediation, and senior employees performing verification that appears nowhere in the AI budget.
This is the Power User Trap℠ operating at portfolio scale. The company removes visible labor while concentrating the hardest review and exception work in a smaller number of experienced employees. The payroll line shrinks. The verification burden relocates.
Removing payroll establishes that payroll was removed. It does not establish that the replacement system is cheaper, more reliable, or financially sustainable.
The CIO and CFO Need the Same Record
The CIO can identify technical consumption and operating dependencies. The CFO can determine whether the associated costs and benefits are economically material. Neither can produce a defensible ROI alone.
Before approving another funding request, leadership should be able to answer:
- What was originally approved, and what is actually operating now?
- What costs have accumulated outside the original business case?
- What human work is still required to produce an acceptable outcome?
- Which claimed benefits have reached revenue, margin, cash flow, or verified cost reduction?
- What additional capital is being requested, and what evidence would cause funding to stop?
If those questions cannot be answered from a reconciled record, the organization does not have an ROI calculation. It has an ROI claim.
Why CFOs Need an AI Capital-Stop Rule
The missing discipline is not another optimistic forecast. It is a refusal threshold.
Before additional funding is approved for an underperforming AI initiative, management should state what evidence would justify retaining, restructuring, impairing, or terminating it. The organization should also define how much more capital may be committed before formal reconsideration becomes mandatory.
The rule does not prohibit further investment. It prohibits further investment by default.
That distinction matters because every pressure surrounding an AI program pushes in the opposite direction: sunk cost, executive mandates, vendor promises, workforce commitments, public strategy, and fear of appearing uncompetitive.
The measure of AI capital discipline is not how the organization funds success. It is whether anyone can stop the funding when success does not arrive.
AI Governance & The Board: Who Can Say “No More Capital”?
AI ROI debt is a governance problem as much as a finance problem. A CFO may see weak economics clearly and still face executive adoption mandates, sunk-cost pressure, vendor promises, workforce commitments, and board expectations that the company remain competitive.
The board’s role is not to select models or manage token consumption. It is to ensure that material AI investments are governed like other capital allocations: with an accountable owner, a reconstructable economic record, and an escalation path when the original assumptions no longer hold.
The board should know who can challenge the next funding tranche, what evidence brings the investment back for review, and who has authority to say no. If no one has standing to invoke the capital-stop rule, the control exists only on paper.
CFO AI Investment Advisory
Lozen Advisory’s CFO AI Investment Advisory provides independent counsel for boards and finance leaders. When the question is whether an unproven AI investment should be rescued or reconsidered, the answer should come from an independent advisor.